Tag: Department of Education

  • Trump Policy Links Student Loans to Job Salaries

    What if your choice of major could determine your access to federal student loans? That’s the reality facing students under a new policy unveiled by the Department of Education on May 3rd. This administration is implementing a rigid ‘Value-Based’ funding model that ties financial aid eligibility to post-graduation salary benchmarks, sparking significant controversy.

    The ‘Earnings Threshold’ and Its Impact

    The core of this new policy is the ‘Earnings Threshold.’ Under these rules, federal financial aid will be revoked for degree programs whose graduates don’t meet specific salary requirements within five years of finishing their studies. While presented as a consumer protection measure, critics argue it unfairly penalizes students who choose socially vital but lower-paying professions.

    Fields like social work, education, community nursing, and the arts are particularly vulnerable. For students passionate about these areas, or those attending smaller regional colleges and minority-serving institutions, this policy creates immense uncertainty. It risks incentivizing a shift away from ‘passion-led’ public service roles towards high-profit corporate sectors, potentially limiting access to higher education for many.

    Concerns for Educational Institutions and Students

    The implications extend to educational institutions themselves. If colleges are forced to shutter programs to maintain federal funding eligibility, students in certain regions might lose access to essential degrees, like early childhood education. Furthermore, the new mandatory Financial Fact Sheets are being criticized for reducing the college experience to a mere financial transaction, overshadowing the civic and intellectual value of higher learning.

    Organizations like the American Association of Colleges for Teacher Education have voiced strong concerns. They predict that if education degrees aren’t recognized as ‘professional,’ enrollment in graduate programs could plummet, leading to higher dropout rates and exacerbating shortages in critical teaching roles.

    A Narrowed Educational Future?

    This federal shift coincides with a broader trend towards efficiency in education, such as three-year degree programs. However, the combination of accelerated learning and these new federal ROI sanctions could lead to a more narrowly focused educational landscape. Future graduates might find themselves steered into highly specialized tracks solely to meet federal salary quotas, potentially diminishing the breadth and depth of knowledge gained.

    This policy raises critical questions about what we value in higher education – is it purely economic return, or does it also encompass personal growth, societal contribution, and intellectual development?

    What are your thoughts on this new policy? Should student loan eligibility be tied to potential future earnings? Share your perspective in the comments below!
  • St. Augustine’s U Backs Trump’s Education Compact

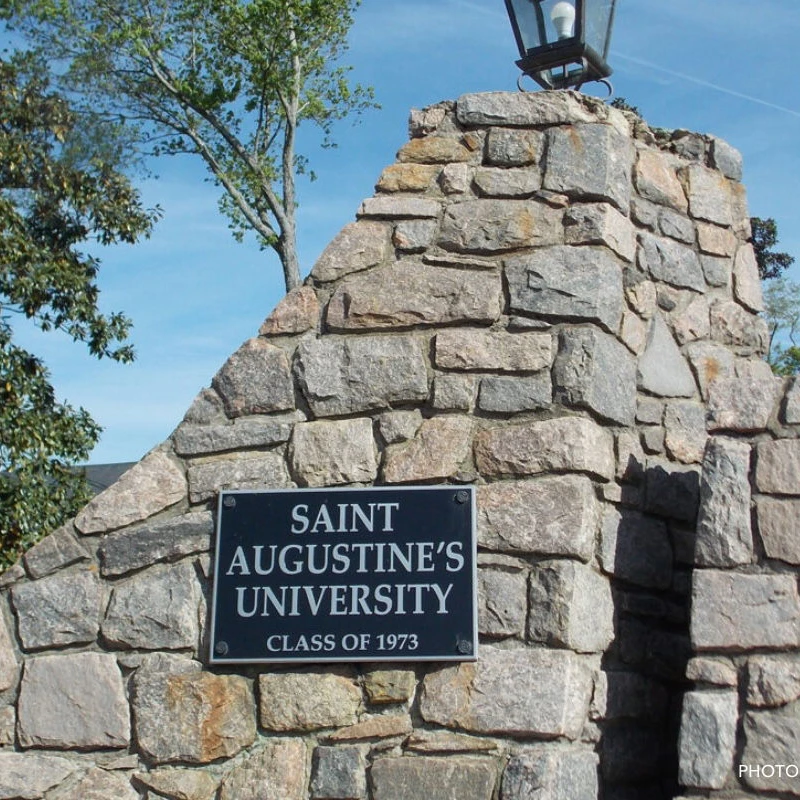
    In a move that has ignited significant backlash from civil rights groups, higher education associations, and academic freedom experts, Saint Augustine’s University (SAU) has become the first Historically Black College and University (HBCU) to publicly support the Trump administration’s proposed “Compact for Academic Excellence in Higher Education.” While other institutions, including Ivy League schools like Brown and Dartmouth, have rejected the compact, SAU has expressed interest in participating.

    A Controversial Compact for Higher Education

    The Trump administration’s compact outlines a series of policy changes that institutions would need to enact to receive preferential funding. These proposed changes are wide-ranging and have drawn sharp criticism for potentially undermining core principles of higher education. The compact requires schools to ban the consideration of race or sex in hiring and admissions, freeze tuition for five years, limit international undergraduate enrollment, commit to institutional neutrality, mandate standardized tests like the SAT or ACT, define biological sex, and shut down departments perceived as hostile to conservative ideas.

    Many experts view this initiative as an attempt by the executive branch to bypass Congress and unilaterally alter the relationship between the government and higher education institutions. Adam Harris, a senior fellow at New America, described the compact as striking “at the fundamentals of higher education,” explaining the vocal opposition it has generated.

    SAU’s Financial Struggles and Stated Alignment

    Saint Augustine’s University acknowledged the significant challenges the compact presents, particularly concerning the ban on race-conscious admissions and international partnerships, which are crucial for many HBCUs. However, the university is reportedly facing ongoing financial difficulties. Earlier this year, SAU lost its accreditation from the Southern Association of Colleges and Schools Commission on Colleges (SACSCOC) due, in part, to its financial crisis, and is currently in legal proceedings to maintain its accreditation. The IRS has also filed multiple tax liens against the university, totaling nearly $10 million.

    Despite these challenges, SAU leaders, including interim president Verjanis Peoples and board chair Sophie Gibson, stated in a letter obtained by Fox News Digital that they see alignment between the compact’s goals and their mission. “As one of the nation’s oldest Historically Black Colleges and Universities, with a 158-year legacy of expanding educational opportunity and transforming lives, we support the Compact’s broad goal of strengthening academic excellence, accountability, and transparency across American higher education,” the letter reads. They expressed eagerness to “collaborate on a grant that is rigorous, mission-aligned, and reflective of America’s diverse higher education landscape.”

    Widespread Opposition and Concerns

    The decision by Saint Augustine’s University has drawn sharp criticism, especially given that six of the nine original institutions invited to review the proposal rejected it. Critics argue that the compact’s stringent requirements could stifle intellectual diversity, limit educational opportunities, and fundamentally alter the nature of higher education in the United States. The university’s financial situation is seen by some as a potential factor influencing its decision to engage with the administration’s proposal.

    What are your thoughts on Saint Augustine’s University’s decision to support the Trump administration’s education compact? Share your opinions in the comments below.

  • Gen Z Turns to Grad School Amid Job Market Woes

    Feeling the pressure of a challenging job market? You’re not alone. Gen Z graduates are increasingly turning to business and law schools, seeking advanced degrees as a way to navigate rising unemployment and the growing impact of AI on the workforce. It’s a strategy reminiscent of the 2008 financial crisis, as the youngest generation safeguards their future.

    A Surge in Graduate Applications

    The numbers don’t lie. Applications to American Bar Association-accredited law schools have seen a significant jump, up 33% compared to last year, according to the Law School Admission Council. Even more telling, the number of first-time LSAT test-takers increased by 25% for the August and September tests this year, adding nearly 5,000 new hopefuls.

    It’s not just law schools seeing this trend. Applications for graduate management education (GME) programs, including MBAs and other business master’s degrees, are also on the rise. After a 12% increase in 2024, GME applications grew by an additional 7% in 2025. Notably, applications to MBA programs from women surpassed those from men this year.

    Navigating the Financial Landscape

    This surge in applications comes at a critical time, as changes to federal student loan policies are set to take effect. The Trump administration’s “One Big Beautiful Act,” signed in July 2025, eliminates the federal Graduate PLUS Loan for new borrowers starting July 1, 2026. This will significantly alter how graduate and professional students finance their education.

    Under the new regulations, federal borrowing limits will be capped. Graduate students can borrow up to $20,500 annually, with a lifetime maximum of $100,000. Professional students, like those entering law or medical school, are eligible for up to $50,000 per year, capped at $200,000 lifetime.

    Why the Shift to Higher Education?

    The unemployment rate for Gen Z hovers around 8.2%, considerably higher than the national average of 3.5% and at its peak since early 2021. Companies like Target and Amazon have announced significant layoffs, and the increasing automation driven by AI tools suggests more job roles may be reduced or eliminated.

    In response to this economic uncertainty and the evolving job market, pursuing higher education appears to be a strategic move for many young individuals. It’s a way to gain specialized skills, enhance marketability, and potentially secure a more stable career path in a rapidly changing world.

    Are you a Gen Z student considering graduate school? How do the new loan regulations impact your plans? Share your thoughts and experiences in the comments below!

  • Judge Orders Trump Admin to Restore School Mental Health Grants

    In a significant victory for student well-being, a federal judge has ordered the Trump administration to reinstate millions of dollars in grants designated for school mental health services. This decision reverses a controversial move to cancel funding that supported the hiring of crucial mental health counselors and social workers in schools across the country.

    A Judicial Reversal on Funding Cuts

    U.S. District Court Judge Kymberly K. Evanson issued a preliminary ruling mandating the restoration of grant funding. These grants, initially part of the Congressionally-funded 2022 Bipartisan Safer Communities Act, were designed to address a growing student mental health crisis, particularly in the wake of tragic school shootings like the one in Uvalde, Texas. The act aimed to pour federal dollars into schools to bolster mental health resources.

    However, the Department of Education (DOE) under the Trump administration decided to withhold over $1 billion in funding. The DOE claimed the grants violated federal civil rights law, specifically citing opposition to diversity, equity, and inclusion (DEI) practices. This stance was taken despite evidence that the grants had already proven effective in districts that received them.

    Impact on Schools and Students

    The consequences of these cuts were felt acutely in districts like Corbett, Oregon. Superintendent Derek Fialkiewicz shared that the grants had enabled his district to more than triple its mental health professionals, going from just two counselors for 1,100 students to a more sustainable number. He emphasized the critical need for these services, especially post-COVID.

    Judge Evanson found the federal agency’s decision to be both arbitrary and capricious. She noted that Congress had specifically created these programs to meet states’ needs for school-based mental health services and had consistently reaffirmed their importance through reauthorization and increased appropriations. Crucially, the ruling stated there was no evidence the Department had considered relevant data about the grants themselves before making the decision to cut them.

    Restoring Funds to Affected States

    This ruling means that funding will be reinstated to Democratic-led states and districts. For example, Madera County, California, is set to receive close to $3.8 million back, while Marin County in the same state will get an $8 million boost. States like Maine, which used the grants to hire 10 new mental health workers and retain four more across nine rural districts, are also expected to benefit.

    The Trump administration’s justification for the funding cut, based on the idea that some aspects of the grant touched on race and were therefore harmful to children, has been directly challenged by this judicial decision. The court’s intervention underscores the importance of these mental health resources for students across the nation.

    What are your thoughts on this court ruling? How important do you believe school mental health services are? Share your opinions in the comments below!

  • DOE Cancels $350M in HBCU Grants

    Big news out of the U.S. Department of Education is sending shockwaves across campuses nationwide. The department has confirmed it’s slashing $350 million in federal grants that were allocated for Historically Black Colleges and Universities (HBCUs) and other minority-serving institutions. While the DOE is calling it a “restructuring effort,” many HBCUs are feeling the sting of this decision, viewing it as a significant blow to vital programs.

    What’s Being Cut and Why?

    These cuts target crucial initiatives designed to bolster HBCUs, expand STEM education for underrepresented students, and provide essential institutional support for minority-serving colleges across the country. For many of these institutions, which often operate on tight budgets, losing this funding could mean serious disruptions to everything from classroom resources and lab equipment to the very programs students rely on.

    Secretary Linda McMahon and the Department of Education are framing this as a “re-envisioning” of how they support underserved students. However, critics, including lawmakers and student advocates, argue this perspective overlooks the real-world impact. These grants aren’t just numbers on a spreadsheet; they fund mentorship programs, faculty development, and access to technology that directly benefits thousands of students.

    The High Stakes for HBCUs

    For many HBCUs, these federal grants are the lifeline that keeps essential programs running. Unlike larger universities that might have deeper financial reserves, smaller institutions, many of which are HBCUs, may struggle to absorb such a significant funding shortfall. This could mean stalled STEM pipelines, fewer research opportunities, and a reduction in vital student support services.

    This decision comes at a time when HBCUs are gaining more visibility and recognition, yet still face numerous challenges. The DOE’s move threatens to undo years of progress in diversifying higher education and ensuring equitable access for marginalized students. Lawmakers like Senator Patty Murray have already voiced strong opposition, warning that the department is jeopardizing resources that Congress has historically championed.

    Student Impact and Future Actions

    The consequences for students could be immediate and profound. Reduced funding for tutoring, research facilities, internships, and scholarships translates directly into fewer opportunities for students to succeed. Faculty are concerned that program closures could negatively affect student retention rates and deter prospective students from enrolling.

    This situation adds yet another layer of pressure on HBCUs, which are already grappling with limited funding, rising operational costs, and recent security threats. The backlash is expected to continue, with potential congressional hearings and legislative efforts to restore the funding. While the Department of Education claims it will redirect resources, HBCU leaders are emphasizing the need for stable, consistent support to ensure these institutions can continue empowering the next generation.

    What are your thoughts on the Department of Education’s decision to cut HBCU grants? How do you think this will impact students and institutions? Share your perspective in the comments below!

  • What to Do About Student Loan Wage Garnishment

    The pause on federal student loan collections has ended, and for the millions of borrowers in default, wage garnishment is a real possibility. The Department of Education began collecting unpaid student loan debt in May 2025, and unlike private lenders, the government has significant powers to recoup these funds. If you’re facing wage garnishment for defaulted federal student loans, it’s crucial to understand your rights and options.

    Understanding Wage Garnishment

    Wage garnishment occurs when your employer is legally ordered to withhold a portion of your paycheck to pay off a debt. For federal student loans in default, your loan servicer can order your employer to withhold up to 15% of your disposable pay. Importantly, the servicer does not need a court order to initiate this process, but you are entitled to 30 days’ notice before garnishment begins. This notice should explain your rights to challenge the garnishment or explore alternatives.

    If you’re unsure about your loan status, you can check your account on StudentAid.gov. If your dashboard indicates “default,” you are at risk of wage garnishment, and you should see a warning at the top of the page. Acting quickly is essential to protect your income.

    Options to Get Out of Default

    If your wages are being garnished or you’re at risk, there are several ways to get out of default and avoid having your pay withheld. One primary strategy is to bring your loan back into good standing through one of these methods:

    • **Pay your loan balance in full:** While often impractical due to the large sums involved, this is the most direct way to resolve default.
    • **Loan Rehabilitation:** To rehabilitate your loan, you must make nine voluntary, on-time payments within 20 days of the due date over a 10-month period. Your loan servicer will determine affordable payment amounts.
    • **Loan Consolidation:** You can consolidate a defaulted federal loan into a new Direct Consolidation Loan. This requires agreeing to repay the new loan under an income-driven repayment (IDR) plan or making three consecutive voluntary, on-time payments on the defaulted loan before consolidating.

    Both loan rehabilitation and consolidation are generally beneficial options. It’s important to note that Direct Consolidation Loans are specifically offered by the Department of Education and differ from private debt consolidation loans, which may not be suitable for borrowers in default and could lead to the loss of federal borrower benefits.

    Other Strategies to Avoid Withholding

    Beyond getting out of default, there are other ways to potentially avoid wage garnishment:

    • **Negotiate your loan repayment:** You can try to reach a voluntary agreement with your lender for payment terms, but this requires their consent and making the first payment within 30 days of receiving the garnishment notice.
    • **Request a hearing:** You have the right to request a hearing to challenge the validity of the debt or argue that garnishment would cause extreme financial hardship. You can also argue if you’ve had limited employment history after involuntary separation. Requests must be submitted in writing, postmarked within 30 days of the default notice, and include supporting documentation.

    Exploring Payment Plans and Relief

    Consider signing up for **income-driven repayment (IDR) plans**, which cap your monthly payments based on your income. While some IDR options are currently on hold, you can still sign up, and some plans may result in a $0 monthly payment. Contact your loan servicer for details and application procedures.

    You may also be able to **pause payments** through deferment or forbearance. Deferment can prevent interest accrual on subsidized loans, while interest accrues on all loans during forbearance. Your eligibility for these options depends on specific circumstances, so consult your loan servicer.

    If you have other debts, **debt settlement** might provide financial flexibility to manage your student loans. This involves negotiating with creditors to pay less than the full amount owed. Even considering **bankruptcy** for other debts could free up funds to address student loans and avoid garnishment, as student loans are typically difficult to discharge in bankruptcy.

    If you’re at risk of wage garnishment, it’s crucial to act swiftly. Explore these options and contact your loan servicer to develop a plan. What steps are you taking to manage your student loan debt? Share your strategies in the comments below!