Category: Financial Empowerment

  • Brooklyn Founder Builds Generational Wealth for Black Families

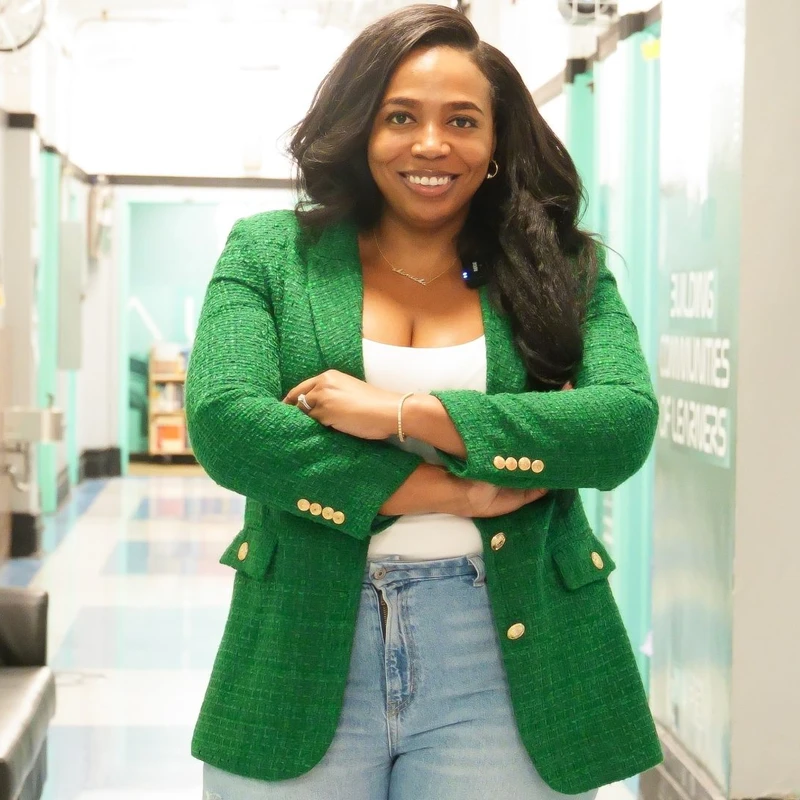
    The statistics are stark: median Black households hold significantly less net worth than White households. While systemic racism has played a major role in this disparity, the path forward requires proactive solutions within our own communities. Enter Shanisha Dixon-Tyrell, a Brooklyn-based finance expert who isn’t just talking about change – she’s actively building it through her FinLit Youth Conference.

    From Finance Professional to Empowerment Advocate

    With over a decade of experience in the finance industry, Shanisha Dixon-Tyrell, a graduate of SUNY Albany, felt a calling to empower others. Working at the New York State Department of Labor, she realized her passion lay in prevention and education, not just navigating financial aftermath. This led her to found Shanisha’s Changing Lives, Inc., a firm dedicated to making financial knowledge accessible and actionable.

    Her personal mantra, “be the change you wish to see,” fueled the creation of the FinLit Youth Conference. Dixon-Tyrell recognized the struggle of not knowing crucial financial practices and vowed to equip the next generation with the tools to avoid similar hardships. She believes making budgeting and investing as routine as daily hygiene is essential for a healthier financial future.

    Bridging Generations for Lasting Wealth

    The FinLit Youth Conference, now in its third year, is a free, annual event designed for youth ages 12-18 and their parents or caregivers. Dixon-Tyrell intentionally includes both age groups because she understands that true financial transformation happens within families. “Generational wealth is great,” she notes, “however when the generations don’t meet, build, and understand the plan it can lead to legacies that don’t last.”

    Dixon-Tyrell emphasizes the historical exclusion of Black communities from wealth-building opportunities due to practices like redlining and predatory banking. By fostering financial independence within the community, she aims to ensure that families can “obtain and sustain their own resources so that no one can ‘cut off our water.’” For young people, this knowledge serves as vital armor.

    Practical Steps for Parents

    1. Demystify the Bank: Take children to the bank, show them ATMs, and explain deposits and withdrawals.
    2. Mind Your Words: Instead of saying “I’m broke,” explain financial priorities to foster critical thinking and respect for money.
    3. Find a Community: Attend events like the FinLit Youth Conference or seek local workshops to normalize and celebrate financial discussions.
    4. Create a Payment System: Implement a system for chores or school achievements, teaching kids to budget, save, and set financial goals with their earnings.

    Starting Early: The Best Age for Financial Education

    Dixon-Tyrell advises starting financial conversations as soon as a child can identify or ask for something they want. Children aged birth to eight are like sponges, building lifelong habits. Teaching them that money is often a result of effort and allowing them to use their own earned money for purchases helps develop decision-making, responsibility, and prioritization skills.

    Beyond Budgeting: Earning and Innovating

    This year’s FinLit Youth Conference promises exciting, hands-on learning experiences. Attendees won’t just learn to save; they’ll learn to earn! The conference features workshops on monetizable skills like hair-braiding, candle making, electrical work, AI app building, and commercial animation, led by young entrepreneurs. They’ve even funded a mobile golf course to teach networking skills in environments where major deals are made.

    A mind, once stretched, can never go back to its original dimensions. That is what the conference does, it stretches you, gives you vision and hope. — Shanisha Dixon-Tyrell’s Mentor

    Shanisha Dixon-Tyrell’s work is a powerful example of how education and community action can combat the racial wealth gap. By equipping Black families with financial literacy, she’s not just teaching skills; she’s fostering hope and building a foundation for lasting generational wealth. What financial lessons did you learn growing up, and what do you wish you knew earlier? Share your thoughts in the comments!

    What are your thoughts on Shanisha Dixon-Tyrell’s approach to building generational wealth? Share your insights and experiences with financial literacy in the comments below!
  • Black Financial Influencers Bridge Wealth Gap

    Remember when talking about money felt like it was only for bankers and the super-rich? Well, the game has changed! A powerful new generation of Black financial influencers is stepping up, using social media and multimedia platforms to break down complex money topics. They’re making financial literacy accessible and relevant, especially for communities that have historically been underserved by traditional institutions.

    Democratizing Financial Knowledge

    For too long, high-level financial education was locked behind exclusive doors. But these digital pioneers are changing that. They’re not just sharing tips on budgeting and investing; they’re weaving in a deep understanding of systemic challenges that disproportionately affect Black communities. This intersectional approach is crucial for dismantling the wealth gap and paving the way for sustainable financial independence and generational wealth.

    Meet the Trailblazers

    Let’s shine a spotlight on some of the incredible voices leading this movement:

    • **Tiffany Aliche (The Budgetnista):** A former preschool teacher turned bestselling author and financial educator. Through her Live Richer Academy, she offers practical lessons on credit repair and saving, having helped her community collectively reduce hundreds of millions in debt since 2008.
    • **Rashad Bilal and Troy Millings (Earn Your Leisure):** These entrepreneurs founded a multimedia platform blending investment education with community storytelling. They host Invest Fest, a major event aimed at making financial growth aspirational for the Black community, focusing on the intersection of entrepreneurship and pop culture.
    • **Bola Sokunbi (Clever Girl Finance):** Launched in 2015, this platform provides a judgment-free space for women seeking financial independence. Sokunbi specializes in debt management and long-term investment, offering books and digital courses.
    • **Dasha Kennedy (The Broke Black Girl):** Kennedy uses social media to advocate for financial equity, discussing workplace income inequality and helping women break the “paycheck-to-paycheck” cycle since 2017.
    • **Tonya Rapley (My Fab Finance):** Established in 2013, Rapley champions practical empowerment, focusing on debt management and long-term planning. She teaches specific budgeting techniques to help individuals regain control of their finances.
    • **Chris Browning (Popcorn Finance):** This podcast breaks down personal finance topics in short, easy-to-understand episodes, designed to reduce money-related anxiety and offer actionable tips for daily financial decisions.

    These influencers are more than just content creators; they are educators, advocates, and community builders. By sharing their expertise in a relatable and culturally resonant way, they are empowering countless individuals to navigate the complexities of personal finance, build wealth, and secure a brighter financial future for themselves and generations to come.

    Who are your favorite Black financial influencers? What financial advice has made the biggest impact on your life? Share your thoughts and recommendations in the comments below!

  • Retirement Planning: Start Early for Financial Freedom

    Retirement might seem like a far-off dream, but the financial decisions you make right now are the building blocks for your future comfort and freedom. Starting your retirement planning early isn’t just about saving money; it’s about giving yourself peace of mind, independence, and a life filled with possibilities instead of limitations.

    The Power of Starting Young

    Many people wait until their 40s or 50s to seriously think about retirement, but this delay often leads to unnecessary financial stress. When you begin saving and investing in your 20s or 30s, you unlock the incredible power of compound interest. Over decades, even modest contributions can grow into a substantial nest egg, transforming your financial future.

    Starting early also gives you crucial flexibility. You’ll be better equipped to handle economic downturns, adapt to changes in income, and avoid making desperate, last-minute financial choices. Essentially, you take control of your future instead of leaving it to chance.

    Define Your Retirement Vision

    Before you crunch numbers, take a moment to imagine what retirement looks like for you. Do you dream of traveling the world, pursuing a passion project, or spending more time with family? Your vision will guide how much you need to save and the best strategies to get there.

    • **Lifestyle Expectations:** Will it be a simple, modest retirement, or an adventurous chapter filled with travel?
    • **Location Decisions:** Consider the cost of living and tax implications of where you plan to settle.
    • **Healthcare Planning:** Medical expenses are a significant factor; plan for them decades in advance.
    • **Family Considerations:** Will you be leaving an inheritance or supporting adult children?

    Having clear goals provides the motivation needed to make every financial decision an intentional step toward your desired future.

    Cultivating Unshakeable Savings Habits

    The magic of compounding really shines with consistent savings. Even saving just $200 a month can lead to significant wealth over 30-40 years! Automating your savings is key – it ensures consistency and removes the temptation to spend that money.

    Take advantage of employer-sponsored plans like 401(k)s, especially if there’s a company match – that’s essentially free money! If your employer doesn’t offer a plan, Individual Retirement Accounts (IRAs) like Traditional or Roth IRAs offer valuable tax advantages.

    Don’t underestimate the impact of small lifestyle adjustments. Preparing meals at home, opting for reliable used cars, and finding free entertainment can redirect thousands of dollars annually toward your retirement fund.

    Making Your Investments Work Harder

    Strategic investing is your most powerful ally when you start early. Historically, stocks have offered strong long-term returns, making them ideal for younger investors who can ride out market volatility. Bonds offer stability, while mutual funds and index funds provide instant diversification.

    • **Ages 20s-30s:** Focus on aggressive growth stocks for maximum long-term returns.
    • **Age 40s:** Balance growth with stability by adding bonds and dividend stocks.
    • **Age 50s+:** Shift towards more conservative investments to preserve wealth and generate income.

    Diversifying across different asset classes, industries, and regions is crucial to protect against major losses. Consider consulting a fee-only financial advisor to create a personalized strategy.

    Conquering Debt Before Retirement

    Carrying debt into retirement can severely limit your financial freedom. High-interest credit cards, loans, and student debt can quickly deplete your savings. Tackle debt while you have a steady income. The ‘avalanche method’ – paying minimums on all debts while aggressively attacking the one with the highest interest rate – is highly effective.

    Avoid taking on new debt for depreciating assets. For mortgages, consider whether entering retirement mortgage-free aligns with your goals, or if leveraging low interest rates for investment makes more sense for your situation.

    Protecting Your Health and Wealth

    Financial security is meaningless without the health to enjoy it. Sustainable habits around exercise, nutrition, and preventive care can reduce long-term medical costs and improve your quality of life. Regular checkups and adopting healthy routines are investments in both your well-being and your finances.

    Consider Health Savings Accounts (HSAs) for their triple tax benefits, and look into long-term care insurance in your 50s to secure coverage at a lower cost.

    Stay Flexible and Informed

    Life happens! Marriage, career changes, or economic shifts mean your retirement plan needs to be adaptable. Conduct annual reviews to ensure your strategies align with your current reality. Track your progress using apps and online tools to stay motivated and on course.

    What’s one small step you can take today to start preparing for your retirement? Share your plans and tips in the comments below!